
Deep learning meets global financial markets.
A proprietary deep learning engine, trained on public market data, learns the residual structure that conventional factor models overlook. We read it to seek return, and to manage risk.
A proprietary deep learning engine, trained on public market data, learns the residual structure that conventional factor models overlook. We read it to seek return, and to manage risk.
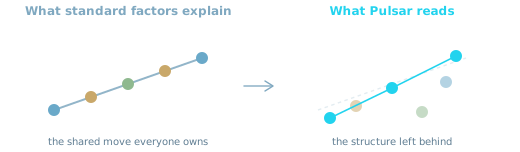
One deep learning engine sits underneath everything we build. It learns the structure that standard factor models leave behind: the part of co-movement they treat as zero. Two focuses read off it, for two different jobs.
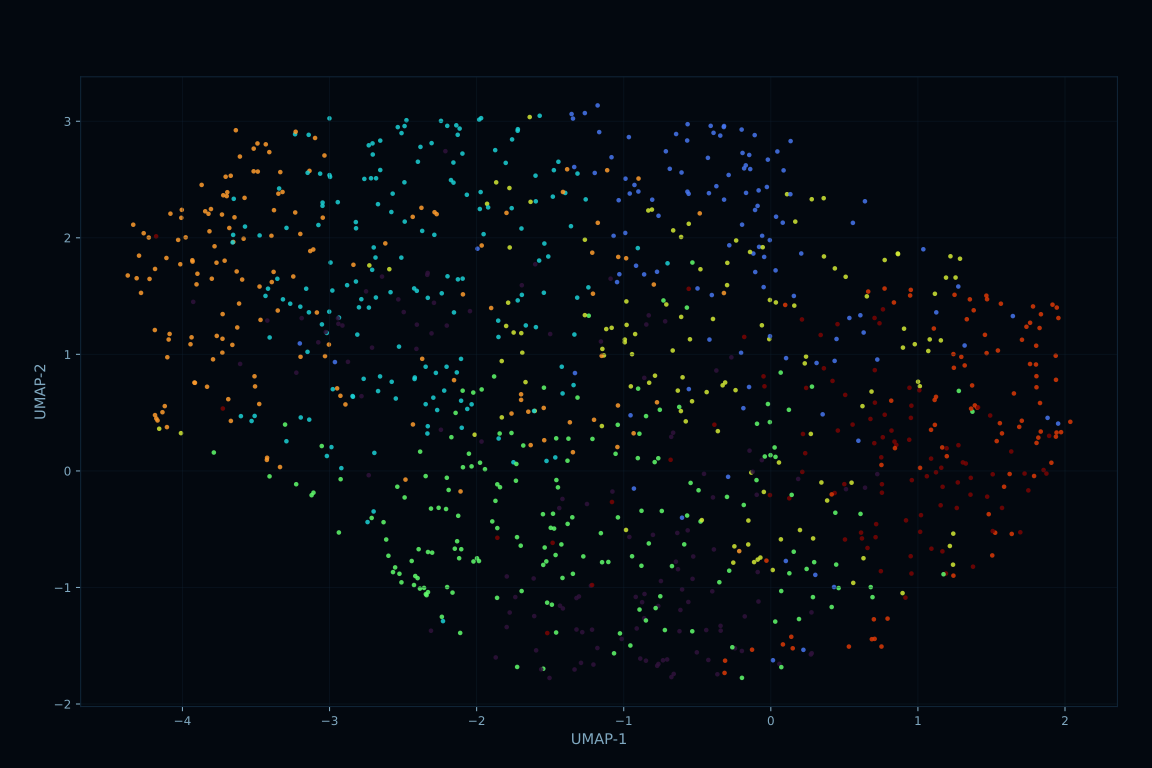
Factor models strip out what they can explain. What remains, the residual, is routinely treated as noise. We think it contains structure worth extracting. Idiosyncratic patterns that can be read systematically, and built into strategies designed to seek return from what others discard.
For allocators and portfolio managers building fresh systematic exposure.
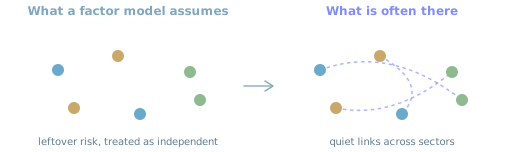
Standard factor-risk models treat residuals as independent. They're not. Hidden co-movement persists inside portfolios, structure that conventional tools don't surface. We read it, and help manage it. Alongside your existing risk workflow, not in place of it.
For risk-aware investors and managers with an existing book.
If you invest systematically, or manage risk for those who do, we'd love to talk.
Or reach us directly at hello@pulsarlabs.co.uk